
Debt Collections for Small Business

Unpaid invoices, delayed payments or disputed debts? Protect your cash flow with Debt Collections for Small Business, using practical recovery solutions and data analysis to avoid common mistakes and improve the chance of getting paid — not merely obtaining a CCJ that may never be satisfied.


Successful debt recovery is not simply about getting a County Court Judgment. Registry Trust’s Q1 2026 data shows that only 11.8% of judgments on the Register were marked satisfied, meaning most CCJs were not shown as paid. Your business needs a structured recovery solution before deciding the next step
Consumer and Corporate Debt Collections
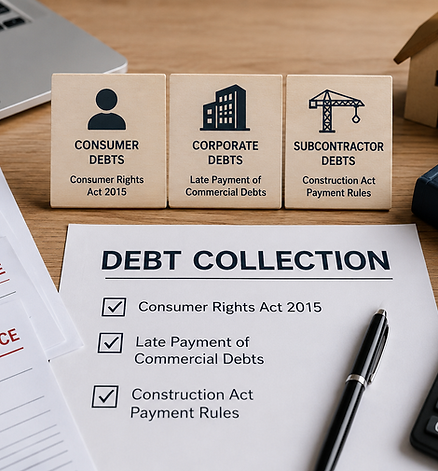
Debt Collections for Small Business should start by identifying who owes the money. A debt owed by a limited company or business customer is not handled in the same way as a debt owed by an individual consumer.
For corporate and B2B debts, the recovery route may involve commercial payment terms, debtor checks and the Late Payment of Commercial Debts legislation.
For consumer debts, the business may need to consider the Consumer Rights Act 2015, including service quality, cancellation rights, fairness and whether the customer has raised a genuine complaint.
Choosing the wrong route can waste time, increase cost and reduce the chance of getting paid.
Button 1:
Corporate Debt Recovery
Button 2:
Consumer Debt Recovery
Some debts need an even more specific route. If the unpaid invoice comes from construction work, subcontracting, applications for payment, payment notices or pay less notices, the debt may need to be reviewed under construction payment rules rather than treated as ordinary invoice chasing.